Creating a Home Inventory for Insurance: Records Worth Keeping
Create a useful home inventory with accurate item details, genuine evidence, dated values, secure backups and clear questions about actual policy limits.
On this page
- Choose a format you can maintain
- Work through the home systematically
- Keep evidence without inventing missing details
- Separate purchase price from replacement estimates
- Use a fictional subtotal carefully
- Protect the inventory and keep a usable copy
- Update when belongings or cover change
- Related guides
- Common questions
- Sources and references
A home inventory is a record of the belongings you would need to describe if something were lost, damaged or stolen. It can also help you review the amount and type of contents cover you hold. The aim is to make accurate information easier to find, not to create a document that guarantees an insurance payment.
This guide explains a practical record-keeping process using official US and Australian consumer guidance checked on 20 October 2026. Insurance definitions and evidence requirements vary by policy and location. All item values in the worked example are fictional, and an inventory total is not a claim settlement estimate.
Choose a format you can maintain
A spreadsheet, structured document or suitable inventory application can all work. Select a method you can update and export, rather than the most elaborate system. If the information is difficult to access when needed, a detailed inventory may be less useful than a simpler, well-organised record.
The US National Association of Insurance Commissioners describes organising belongings by room or category and keeping photographs. Its inventory application is one available example, not a requirement for every insurer. Check any application’s privacy, export and account-recovery arrangements before placing sensitive household information in it.
Give each entry a stable identifier that connects it to receipts and images. A label such as “living-room-camera-01” can prevent confusion between similar items. Keep the naming scheme simple enough that another trusted household member can understand it.
Work through the home systematically
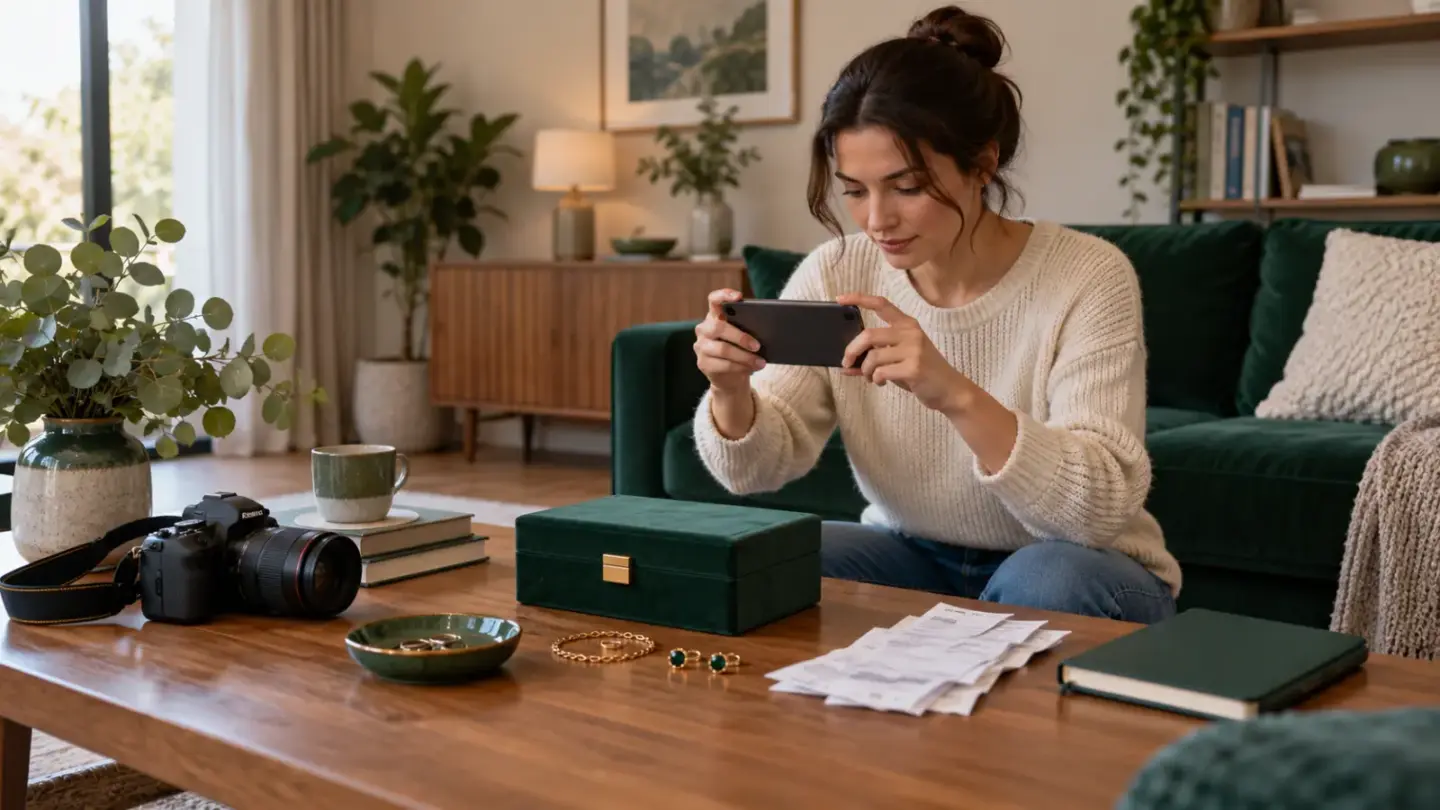
Start with one room and record what is present before moving to the next. Include storage spaces, cupboards and items used only occasionally. A quick room photograph provides useful context, while individual photographs can show details that a wide view misses.
Record portable items that may move between rooms only once. For a camera kept in a study but used elsewhere, choose a main record and note its normal storage location. Duplicating the same item in several room lists can inflate the apparent contents total.
Distinguish household-owned belongings from borrowed, rented or business-owned items. The insurer’s definition of covered property may treat them differently. Likewise, do not assume the building owner’s policy covers a tenant’s personal possessions; confirm the actual arrangement.
| Record | Example of what to keep | Important limitation |
|---|---|---|
| Identification | Description, make, model and serial number | Record actual details, not a similar product’s specifications |
| Purchase evidence | Receipt, date and original price where available | Original price is not necessarily today’s replacement cost |
| Visual record | Room image and clear item photographs | A photo alone may not establish value or ownership |
| Policy questions | Special limits, listing or valuation requirements | The inventory does not change the policy wording |
Keep evidence without inventing missing details
NAIC consumer guidance recommends details such as brand, purchase date, price, model and serial number, supported by receipts and photographs. Record those details accurately where available. If the purchase date is approximate or a receipt is missing, label the uncertainty instead of filling the gap with an invented fact.
Other genuine records may help explain an item, such as an order confirmation, warranty document or repair invoice. Ask the insurer what evidence it can accept for your circumstances. Do not assume that one type of document is mandatory everywhere or that an alternative will always be sufficient.
For gifts, inherited possessions or specialist items, note the available history and any professional valuation. Keep the valuation date and purpose. A valuation for one purpose may not satisfy a particular insurance requirement, so confirm the insurer’s expectations before relying on it.
Separate purchase price from replacement estimates
Maintain different fields for the original price and an estimated current replacement amount if you use both. The first describes a historical transaction; the second is an estimate at a particular date. Neither automatically establishes how an insurer will settle a covered loss.
MoneySmart’s Australian contents guidance explains the importance of checking covered items, events and limits. Ask whether relevant policy terms use replacement, depreciated value or another settlement basis, and whether conditions must be met before additional reimbursement becomes available.
Pay particular attention to categories with special limits, such as jewellery, collections or business equipment where applicable. A detailed list does not override a sublimit or add cover away from home. Record the question and obtain an answer linked to the actual policy.
- Purchase price: what you originally paid.
- Replacement estimate: a dated estimate for a comparable item.
- Claim payment: an insurer’s determination under the actual policy and loss circumstances.
Use a fictional subtotal carefully
Suppose a small room list contains a desk estimated at 300, a chair at 150, a computer at 900 and other recorded items totalling 250. The fictional replacement subtotal is 1,600. It is not the whole home’s contents value unless every relevant item has genuinely been included.
If the computer appears again in a portable-electronics list, adding another 900 would produce an incorrect combined figure of 2,500. Referencing the same item identifier avoids that duplication. Accessories that are genuinely separate should have their own clearly described entries.
Do not subtract an excess or apply a settlement percentage to this inventory as though calculating a guaranteed payout. The event, policy limits, evidence and settlement conditions must all be considered. The example demonstrates bookkeeping accuracy only.
- 300 desk + 150 chair + 900 computer + 250 other items = 1,600.
- Adding the same computer twice would incorrectly produce 2,500.
- Use stable item identifiers to avoid double counting.
- Neither total is a promised insurance payment.
Protect the inventory and keep a usable copy
An inventory can reveal valuable possessions, purchase details and household information. Store it with appropriate access controls, and avoid posting it publicly or sharing an unrestricted link. Give an insurer only the information needed through its genuine submission channel.
The financial-preparedness checklist hosted by Ready.gov recommends securing important records and keeping copies or backups in a safe place. Consider whether a fire, theft or device failure could affect both the original and the only copy. Test that a backup opens and contains the expected information.
Account recovery also matters. Keep an appropriate recovery arrangement so the record is not permanently inaccessible if a device is lost. A trusted person’s involvement should be deliberate and proportionate, rather than automatic access to every unrelated personal file.
Update when belongings or cover change
Add significant purchases, remove disposed items and record moves or major changes in storage. A dated review around policy renewal can help identify questions, although the right frequency depends on how much changes in the household.
After a loss, follow the insurer’s reporting and evidence instructions and prioritise safety. Do not re-enter an unsafe property just to improve the inventory. Keep original records and explain any corrections rather than altering the history to match a desired claim amount.
Use the insurance comparison tool to organise policy questions and the monthly budget tool for premiums or planned replacement saving. Read our financial disclaimer. These tools cannot value specialist possessions or determine claim entitlement.
Related guides
Continue with Home Insurance Replacement Cost vs Actual Cash Value Explained and Renters Insurance: Personal Property, Liability and Common Exclusions. Each guide identifies its scope and any country-specific rules.
Common questions
Do I need a special inventory app?
No. A maintainable document or spreadsheet can also work. Choose a format that supports accurate records, secure storage and a usable export when you need it.
Will an inventory guarantee that my claim is paid?
No. It supports documentation, but payment depends on the policy, covered event, limits, evidence and settlement conditions. An inventory does not create additional insurance cover.
What if I no longer have a receipt?
Record that honestly and retain other genuine evidence where available. Ask the insurer what alternatives it can accept rather than inventing a price or purchase date.
Should I record original or replacement prices?
If useful, keep both in separate dated fields. They describe different things, and neither should be presented as the amount an insurer is guaranteed to pay.
Can one room photograph replace all item details?
A room photograph provides context but may not show models, serial numbers or condition clearly. Combine it with more specific records for items where those details matter.
How do I avoid listing portable items twice?
Give each item a stable identifier and one main entry. Other room or category lists can refer to that entry without adding its value again.
Are borrowed belongings covered automatically?
Do not assume so. Identify ownership accurately and check the policy’s treatment of borrowed, rented or business property before relying on household contents cover.
Does recording jewellery remove a policy sublimit?
No. A record does not override limits or listing requirements. Ask the insurer whether specific cover or an acceptable valuation is needed for the actual item.
Where should I keep the inventory?
Use secure storage with a usable backup that is not exposed to the same single point of failure. Limit sharing because the record can reveal valuable possessions.
Should I enter a damaged property to update records?
Prioritise safety and follow official and insurer instructions. Do not enter an unsafe building simply to gather photographs or improve an inventory after a loss.